Buying a first home in Old Town can feel more manageable when each decision has a purpose: clarify the budget, compare homes carefully, make a prepared offer, and plan for closing. This step-by-step approach helps turn a high-energy Chicago search into a process with clear next moves and fewer avoidable surprises.
Start With the Numbers Before Touring Homes
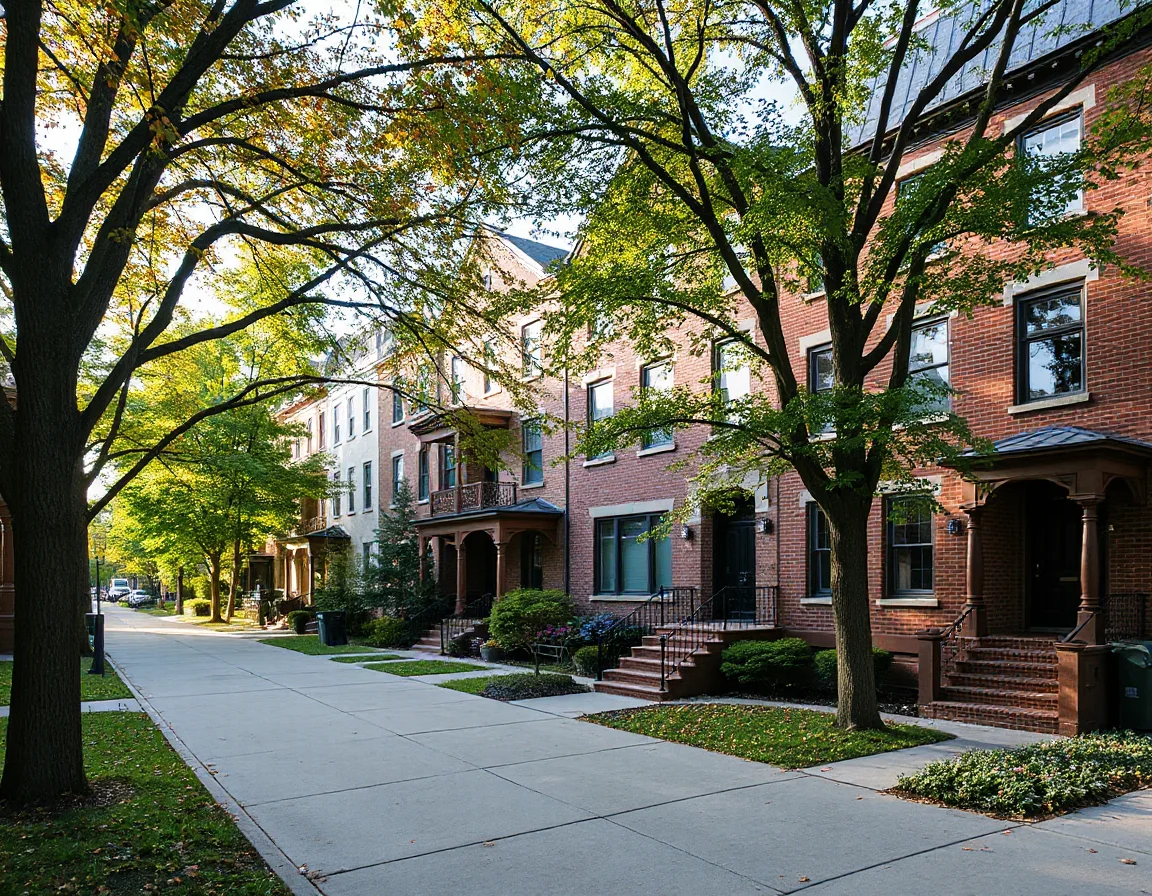
Old Town offers a distinct mix of historic streets, condominium buildings, townhomes, and single-family residences near Lake Michigan, Lincoln Park, and the amenities of the Near North Side. Before scheduling a full weekend of tours, build a realistic purchase budget. The purchase price matters, but it is only one part of the monthly picture: mortgage principal and interest, property taxes, homeowners insurance, association dues when applicable, utilities, parking, and a reserve for repairs all deserve a place in the calculation.
A lender pre-approval is a useful early milestone because it estimates the financing range based on verified financial information. It also gives buyers time to compare loan options, ask about rate locks, and understand projected cash needed at closing. A pre-approval is not a reason to stretch to the top of a lending limit; instead, use it as a framework for deciding what payment leaves room for everyday priorities and homeownership expenses.
For condos and co-ops, request information about monthly assessments, planned capital work, reserves, rental rules, move-in procedures, and any special assessments. These documents help explain how a building is operated and can change the true cost of ownership. For detached homes and townhomes, make room in the budget for maintenance items that an association may otherwise handle, such as exterior repairs, landscaping, roofs, or mechanical systems.
A comfortable monthly payment is more useful than a maximum approval amount. Build your target around the payment, closing funds, and an emergency reserve—not the list price alone.
It also helps to separate closing costs from the down payment. Closing costs can include lender charges, title-related expenses, prepaid items, inspections, attorney review, and other transaction-specific charges. Your lender and real estate team can help outline estimates early, so the cash-to-close figure does not arrive as a last-minute mystery.
Define Your Search Priorities in Old Town
Once the financial range is clear, create a short list of needs, preferences, and trade-offs. In a neighborhood where homes can vary widely by block and building type, this list prevents attractive finishes from distracting from the essentials. Consider the number of bedrooms and bathrooms, preferred floor plan, storage, outdoor space, elevator access, parking, pet policies, association structure, and the condition of major systems.
Think about how the home functions on an ordinary Tuesday, not only how it feels during a showing. Measure key furniture before touring if a particular piece must fit. Notice natural light at different times when possible, assess storage with an eye for daily use, and ask about package delivery, bike storage, laundry, noise-transfer policies, and guest parking. These practical details often determine whether a home continues to work well after move-in day.
Location comparisons can be equally specific. Old Town provides access to green space, transit options, cultural venues, dining, and lakefront recreation, but proximity to each feature differs from one address to another. Map regular destinations, review transit routes, and visit at varying times to observe traffic patterns and street activity. The goal is not to find a universally “best” block; it is to identify the setting that aligns with your own routine and priorities.
A buyer’s agent can organize showings, point out market context, and help you compare the financial and practical differences between properties. In a competitive setting, having a defined decision process means you can move promptly when the right fit appears without losing perspective.
Make an Offer With Facts, Not Guesswork
When you are ready to pursue a property, review recent comparable sales, current competing listings, days on market, and the home’s particular condition. These details help shape an offer strategy that reflects the property rather than headlines about the broader Chicago market. A strong offer is not simply the highest number; it can also include clear financing, an appropriate earnest-money deposit, thoughtful contingencies, and a timeline that the seller can realistically accept.
In Illinois, the attorney-review period is a central part of many residential transactions. After a contract is accepted, attorneys generally review the agreement and negotiate modifications within the applicable review window. This is also an important time to coordinate inspections and examine condominium or association materials. Your attorney, lender, and agent each have different responsibilities, and early communication among them can keep deadlines visible.
An inspection is an information-gathering step, even with a newer or recently renovated home. Inspectors may identify maintenance needs, safety concerns, or systems nearing the end of their expected service life. For condominium purchases, the inspection focuses on the unit, while association documents and building information offer additional context about common elements. Use the findings to understand the property’s condition and discuss reasonable next steps with your professional team.
Offer terms work together. Price, financing, contingency timing, earnest money, and closing date all shape the overall proposal and should be considered as one package.
It is normal for first-time buyers to feel a rush once an offer is accepted. Shift that energy into a checklist: send documents to the lender quickly, schedule inspections, review disclosures, keep large financial changes on hold, and save every transaction document in one folder. Small organizational habits can make the period between contract and closing much calmer.
Prepare for Closing and the First Months of Ownership
As closing approaches, the lender completes final underwriting and prepares the closing disclosure, which outlines the loan terms and estimated final costs. Review it carefully and compare it with earlier estimates. Before closing, complete a final walkthrough to confirm the property is in the agreed condition and that any negotiated items have been addressed. The walkthrough is not another inspection; it is a final confirmation before ownership transfers.
After receiving the keys, prioritize a few foundational tasks: change locks or rekey them, locate shutoff valves and electrical panels, save appliance and warranty information, and establish a maintenance calendar. If the home is in an association, keep building contacts, move-in rules, and meeting information readily available. A first home becomes easier to manage when routine care starts early rather than after a preventable issue appears.
Old Town rewards a deliberate search. By setting a clear budget, comparing homes through the lens of daily use, and building a reliable team for the contract-to-closing period, first-time buyers can approach the process with confidence. The right plan does not eliminate every question, but it gives each question a place to be answered before it becomes a surprise.